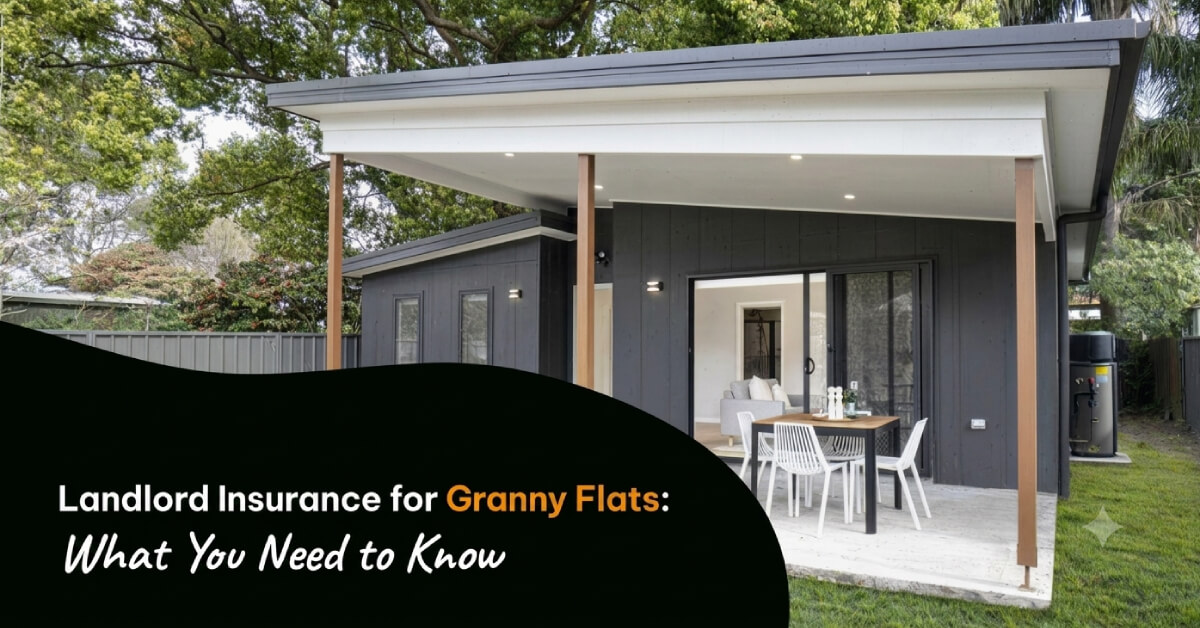
Why Insurance Matters for Granny Flats
Building a granny flat is a significant financial commitment. From construction costs to furnishing and maintenance, the investment can easily reach tens or even hundreds of thousands of dollars. Once tenants move in, additional risks arise, including accidental damage, unpaid rent, and liability claims.
Having the right cover for granny flat investment properties ensures you’re financially protected in the event of unexpected situations. Without proper insurance, even a minor issue could lead to significant out-of-pocket expenses.
Many property owners assume their existing home insurance policy automatically protects their granny flat. However, this isn’t always the case.
Does Home Insurance Cover a Granny Flat?
One of the most common questions homeowners ask is: does home insurance cover a granny flat?
The answer depends on how the granny flat is being used.
If the granny flat is occupied by family members and considered part of your main residence, some home insurance policies may provide partial coverage. However, if you’re renting out a secondary dwelling, insurance requirements usually become more specific.
Once a granny flat is used as a rental property, insurers often classify it differently from a standard home. This means you may require dedicated landlord insurance to ensure proper protection for:
- Tenant-related damage
- Rental income loss
- Public liability claims
- Structural damage
- Legal expenses
Always review your insurance policy carefully and speak with your provider to confirm exactly what is included.
What Does Granny Flat Landlord Insurance Cover?
A quality granny flat landlord insurance policy can protect both the physical structure and the financial aspects of your rental property.
Here are the main types of coverage typically included.
Building Insurance for Granny Flat
Building insurance granny flat coverage protects the physical structure itself. This can include:
- Fire damage
- Storm and flood damage
- Vandalism
- Burst pipes
- Accidental structural damage
If your granny flat includes fixtures such as kitchens, bathrooms, flooring, or built-in wardrobes, these are generally included under building coverage as well.
This type of insurance is particularly important because repairing or rebuilding a granny flat can be extremely expensive without adequate protection.
Tenant Damage Insurance
Even reliable tenants can accidentally damage property. In some cases, malicious damage may also occur.
Granny flat tenant damage insurance helps cover repair or replacement costs resulting from tenant-related incidents, such as:
- Broken doors or windows
- Wall damage
- Carpet stains
- Damage to fixtures
- Intentional vandalism
Without landlord insurance, these costs usually fall entirely on the property owner.
Loss of Rental Income
If your granny flat becomes uninhabitable due to insured damage, landlord insurance may compensate you for lost rental income during repairs.
For example, if a storm damages the roof and tenants need to move out temporarily, your policy may continue to cover lost rent while the property is being restored.
This feature is particularly valuable for owners who rely on rental income to help pay off construction loans or mortgages.
Public Liability Protection
Liability cover protects you if someone is injured on your property and holds you legally responsible.
For example:
- A tenant slips on damaged stairs
- A visitor suffers an injury due to poor maintenance
- Property defects cause accidents
Legal claims can become extremely expensive, making liability protection an important part of protecting your backyard rental.
Common Exclusions to Be Aware Of
Not every issue is automatically covered under landlord insurance. Policies often contain exclusions that property owners should understand clearly.
Common exclusions may include:
- General wear and tear
- Poor maintenance
- Pest infestations
- Intentional illegal activity by tenants
- Unapproved renovations
Reading the Product Disclosure Statement (PDS) carefully can avoid misunderstandings later.
Tips for Choosing the Right Insurance Policy
Not all insurance policies offer the same level of protection. Here are a few important tips when comparing coverage options.
Understand How the Granny Flat Is Used
Insurance needs may differ depending on whether:
- Family members occupy the granny flat
- It is rented short-term
- It is leased long-term
- It is a vacant part of the year
Be transparent with your insurer about how the property is used to ensure proper coverage.
Compare Coverage Limits
Some cheaper policies may have limited coverage for:
- Tenant damage
- Rental default
- Natural disasters
- Legal expenses
Focus on overall value rather than simply choosing the lowest premium.
Consider Contents Insurance
If the granny flat is furnished, contents insurance may protect items such as:
- Appliances
- Furniture
- Curtains
- Air conditioners
This is especially useful for short-term or fully furnished rentals.
Check Excess Amounts
The excess is the amount you pay when making a claim. Lower premiums sometimes come with higher excess fees, so make sure the balance suits your budget.
Protecting Your Investment Long-Term
A granny flat can become a highly profitable long-term asset, especially as housing demand continues to rise across Australia. However, unexpected events can quickly affect your returns if you are not properly insured.
By investing in the right granny flat landlord insurance, you can reduce financial risks while confidently managing your rental property.
Good insurance not only protects the structure itself but also helps safeguard:
- Rental income
- Legal liability
- Repair costs
- Tenant-related risks
- Long-term property value
If you’re building a granny flat or already renting one out, it’s a good idea to check your insurance coverage regularly. This helps you stay on top of your responsibilities as a property owner.
Final Thoughts
Owning a granny flat rental offers excellent income potential, but it also comes with unique responsibilities. Standard home insurance alone may not provide enough protection once tenants are involved.
Understanding the importance of building insurance, granny flat policies, and liability cover, as well as granny flat tenant damage insurance, can help avoid major financial setbacks and keep your investment secure.
The right insurance policy gives you peace of mind while ensuring your backyard rental remains protected for years to come.
If you’re considering the financial side of granny flat ownership, you may also enjoy reading the following: Granny Flat ROI: How Long Does It Take to Recover Your Investment?